
When a company finances its growth in a circle, a supplier holding its stock, a customer holding its stock, a trading firm investing beside a purchase commitment, lenders secured by the contracts among them, the firm’s own ledger stops being the place where returns can be read. A discounted cash flow of the consolidated company returns no answer inside a defensible horizon. The value question moves instead to the participants: what each puts in, what each takes out, where each return accrues, and in what order. This quarter supplied the demonstration. About $1.4 billion made a round trip through the filings, out of deferred revenue with a sentence and back without one, and on August 3 we had published four questions that the August filings have now answered. The answers all point away from the consolidated ledger and toward the participants.

On August 3 we published four questions and wrote that the filings, not the call, would answer them. The filings have printed: the earnings release on August 11, the Form 10-Q the same evening. Here are the answers.
First, the frame. The filings present a company that burns cash, depends on debt, and grows fast: revenue of $2,575 million in the quarter, a net loss of $626 million, operating cash flow that covers net interest expense 1.06 times on our derivation, and $35.6 billion of total indebtedness with about $10.0 billion more committed and undrawn, per the 10-Q. The value story, in cash and not in relative terms, is that the company will ultimately return more than its cost of capital. By the company’s own math that point is years out, and progress toward it is measured against metrics the company defines: backlog, contracted power, and a family of adjusted measures. Two other statements in the same filing complicate the reading. The auditor’s critical audit matter sits on revenue recognition. And material weaknesses in internal control over financial reporting “continued to exist as of June 30, 2026.”
And then there is the $1,469 million that appeared under a new caption in one quarter and disappeared in the next. It lives at the intersection of those two complications. We will come to it.
The second question: what resolves the $1.3 billion?
In August we asked what would become of the amount reclassified out of deferred revenue in the first quarter: does it “earn into revenue as the machines deliver, settle as a note, a reversal, a return of cash, or a charge, resolve in a way no filing has shown, or simply stand another quarter?” The answer is a reversal. Of the outcomes on that list, it is the one the filings performed without narrating.
The record, in sequence. The FY2025 10-K carries no caption called “customer liabilities” anywhere; other current liabilities stood at $162 million, not itemized. The Q1 10-Q created the caption: its balance sheet components note showed customer liabilities of $1,469 million at March 31, and its revenue note narrated the arrival, a change in deferred revenue “primarily driven by reclassification of $1.3 billion to customer liabilities.” The Q2 10-Q does not contain the phrase at all. The line’s parent, other current liabilities, fell to $70 million, again not itemized. The caption was born on March 31 and was gone by June 30. Its entire life was lived in interim statements, which are reviewed, not audited.
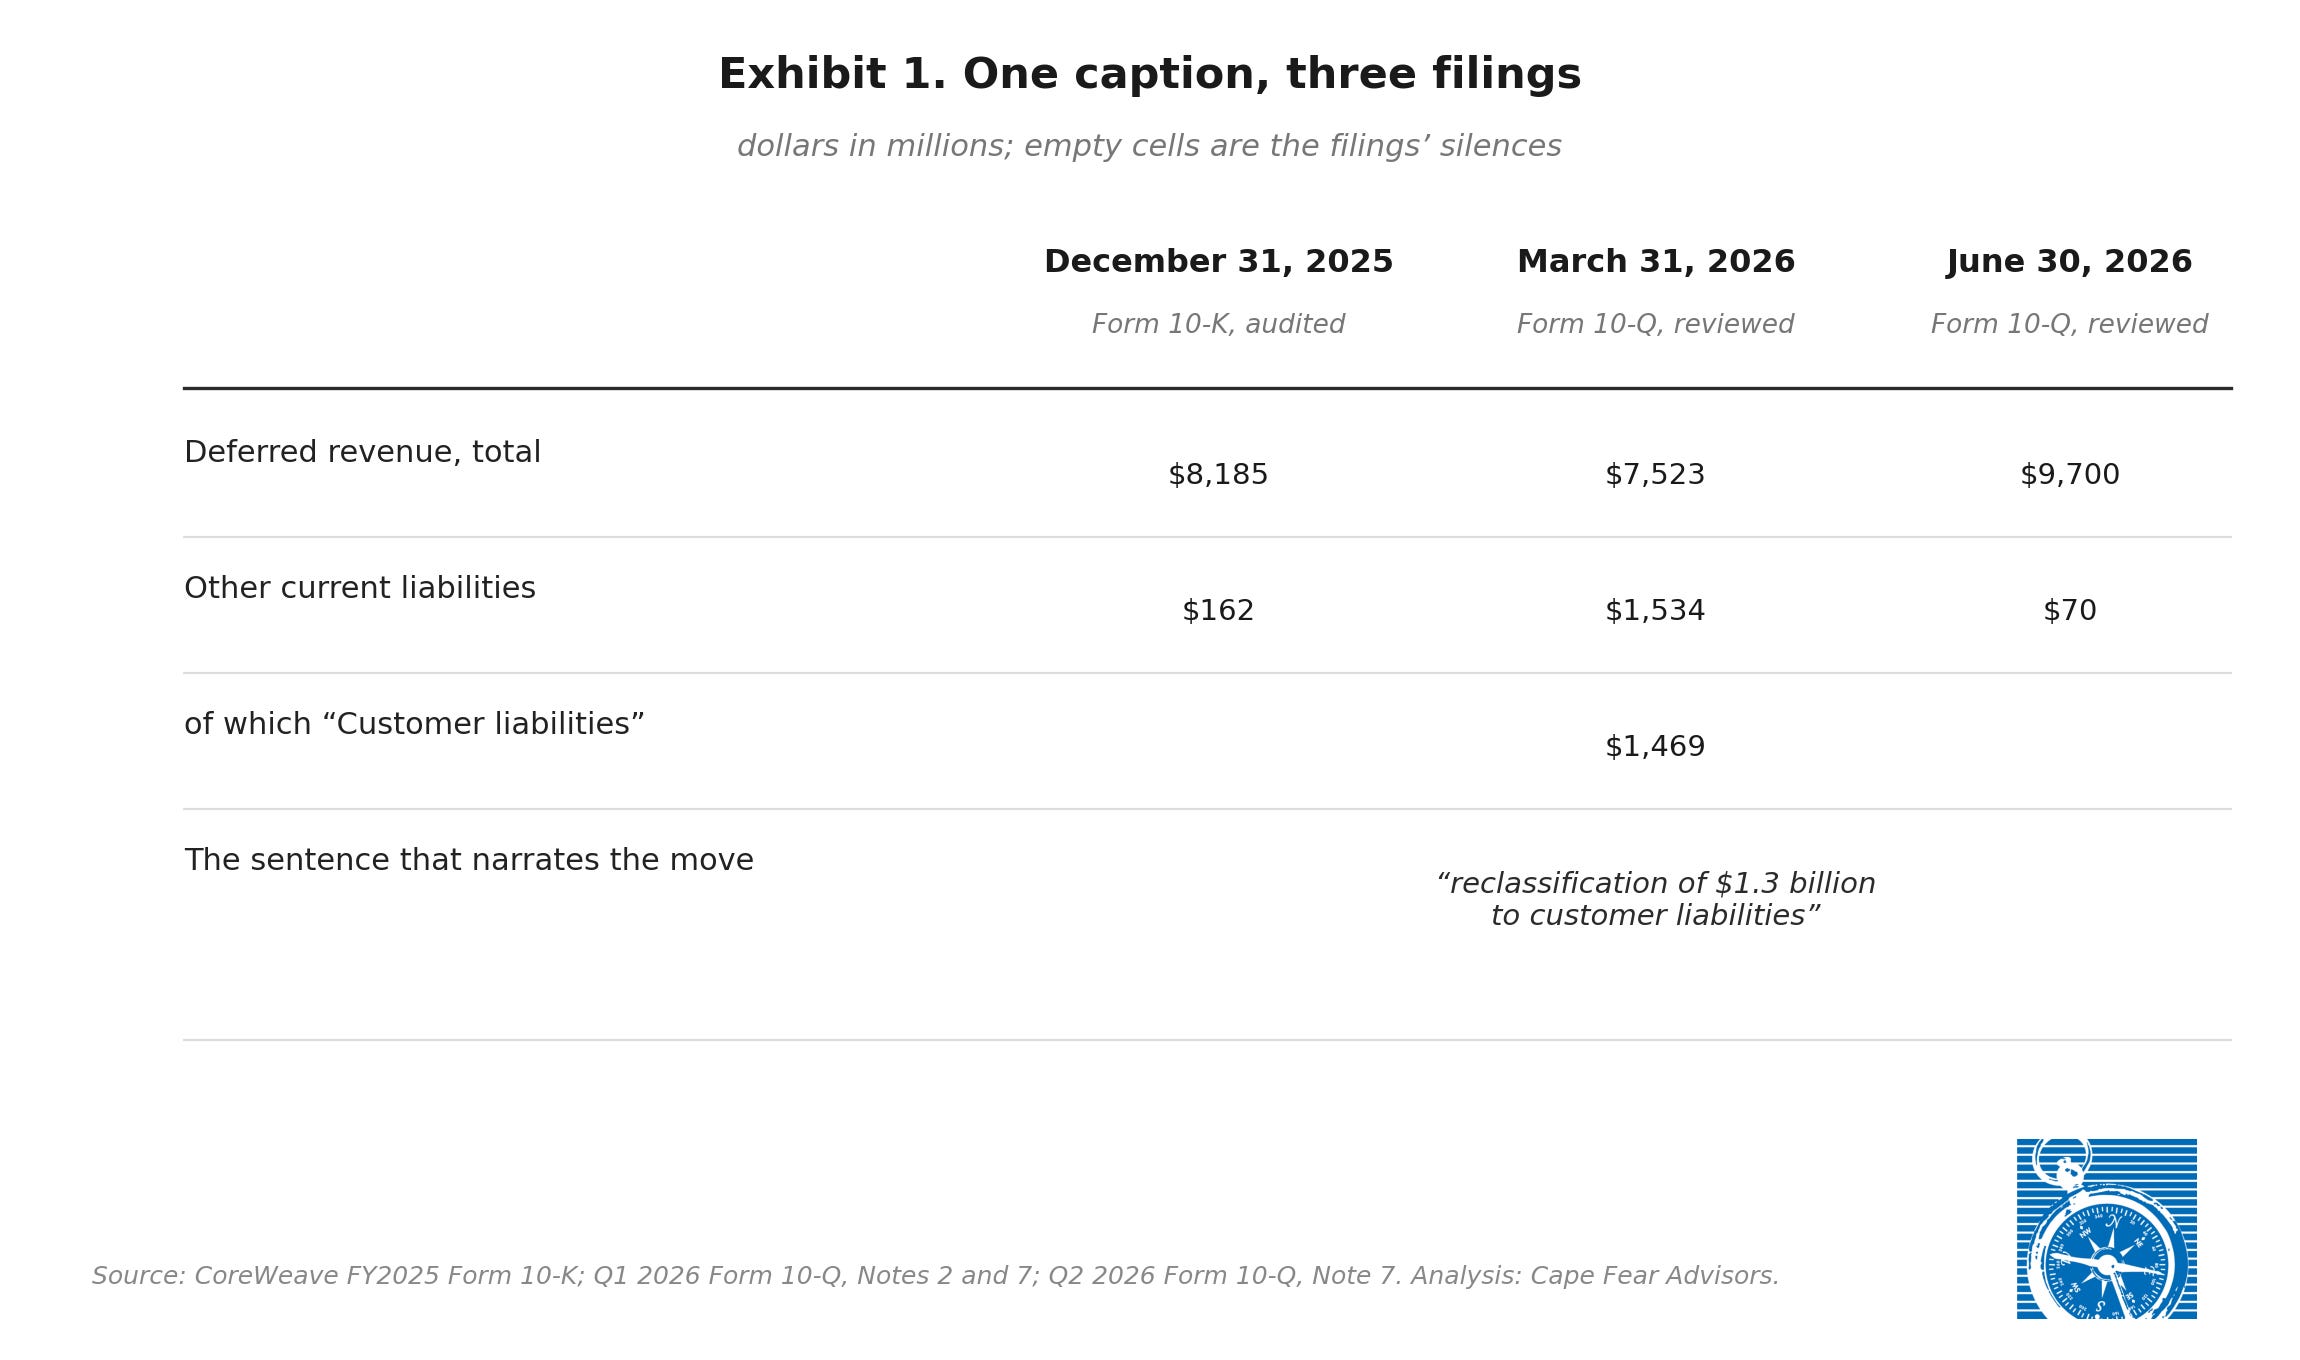
The caption is gone. The money is not. The reclassifications are non-cash, so each period’s gap between the change in the deferred revenue balance and the deferred revenue line inside operating cash flows measures the non-cash movement. In the first quarter, the balance fell $662 million while the cash flow line contributed positive $575 million: a non-cash exit of about $1.2 billion, matching the narrated $1.3 billion within ordinary residuals. Across the first half, the balance rose $1,515 million against a cash flow line of $1,365 million: a non-cash movement of only $150 million for the six months combined. The subtraction is ours and it is short: the second quarter alone contains a non-cash movement of roughly $1.4 billion back into deferred revenue, against the $1,469 million balance that vanished. The money sits where it started, under the name it had before it left.
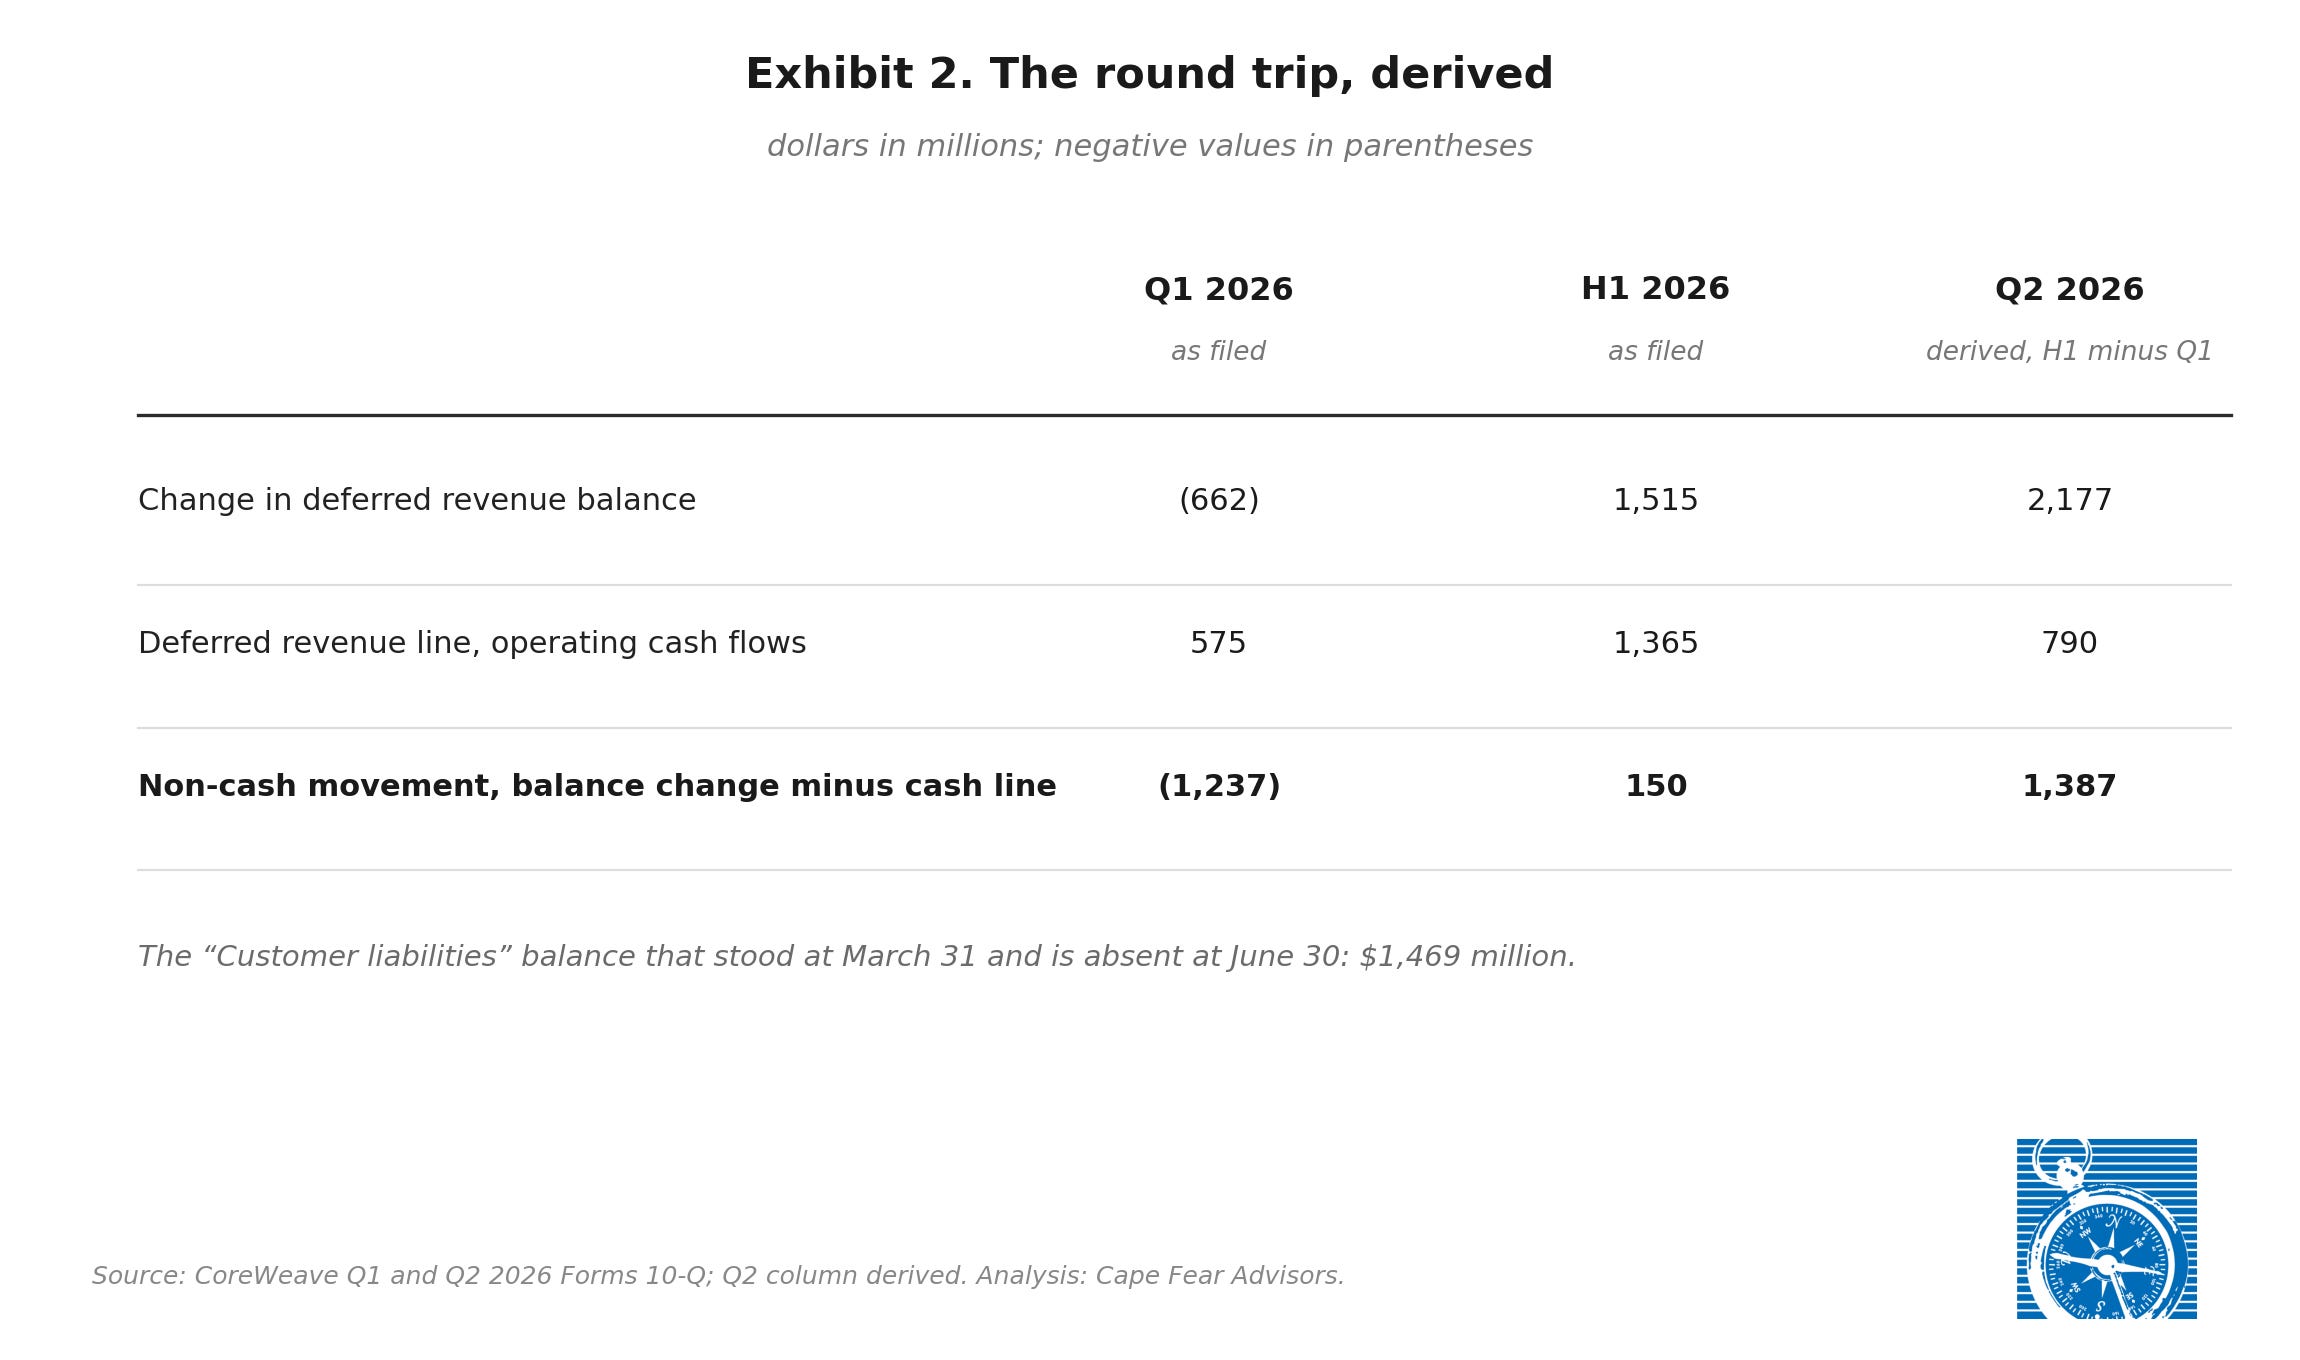
One precision point. These movements are non-cash; they inflated no quarter’s operating cash flow in either direction. The cash is real. The question was where the obligation stood, and under what name, and the answer is that it made a round trip through a caption that no longer exists. Out of deferred revenue with a sentence. Back without one.
The third question: does the largest customer’s share keep falling?
It fell again. The 10-Q reports the top three customers at approximately 36, 26, and 10 percent of quarterly revenue, against a single customer at 71 percent in the prior-year quarter. The 10-Q does not attach names to the percentages. It does attach commitments: an order form with OpenAI of approximately $6.5 billion running through May 2031, an order form with Meta of approximately $21.0 billion signed in March, and, per the release, more than $25 billion of net new commitments in early Q3 against a backlog of $104 billion. One sentence in the risk factors is new to us: “our current customers have contractually specified our use of NVIDIA GPUs.” Diversification of names, concentration of chain.
The first and fourth questions: which rung, and does cash arrive from outside?
In August we asked which rung the quarter’s solution would sit on, a new one or cash off an old one, and whether cash arrives from outside. The answers arrived together. Cash arrived, mostly borrowed, at a rising price, on a new rung. Financing activities supplied $14.0 billion in the first half, net: $16.7 billion of debt proceeds and $3.0 billion of private placement equity, less $5.2 billion of debt repayments and $0.5 billion for capped calls. On our derivation, $10.1 billion of that net arrived in the second quarter, against $3.7 billion of operating cash flow for the half. Most of that operating cash arrived on the first quarter’s working-capital tide, chiefly a receivables collection above $1 billion; the second quarter contributed $679 million. And first-half debt service, $5.2 billion of principal plus $982 million of interest per the 10-Q, exceeded the half’s operating cash flow by about $2.5 billion. The company’s new facility, DDTL 5.5, priced at SOFR plus 5.50, one hundred basis points wider than the facility signed in May at the same ratings from the same agencies, with the release naming what changed: earlier facilities were backed by customer contracts running through the debt’s maturity, and the new one carries a five-year term against three-year contracts. That facility is the new rung. On the equity side there was one outside check: Jane Street’s $1 billion investment in April, announced alongside a $6 billion commitment to purchase compute. We flagged that transaction in a correction to our August 11 piece, and it counts on both sides of this question, outside capital and a commercial commitment arriving in the same announcement.
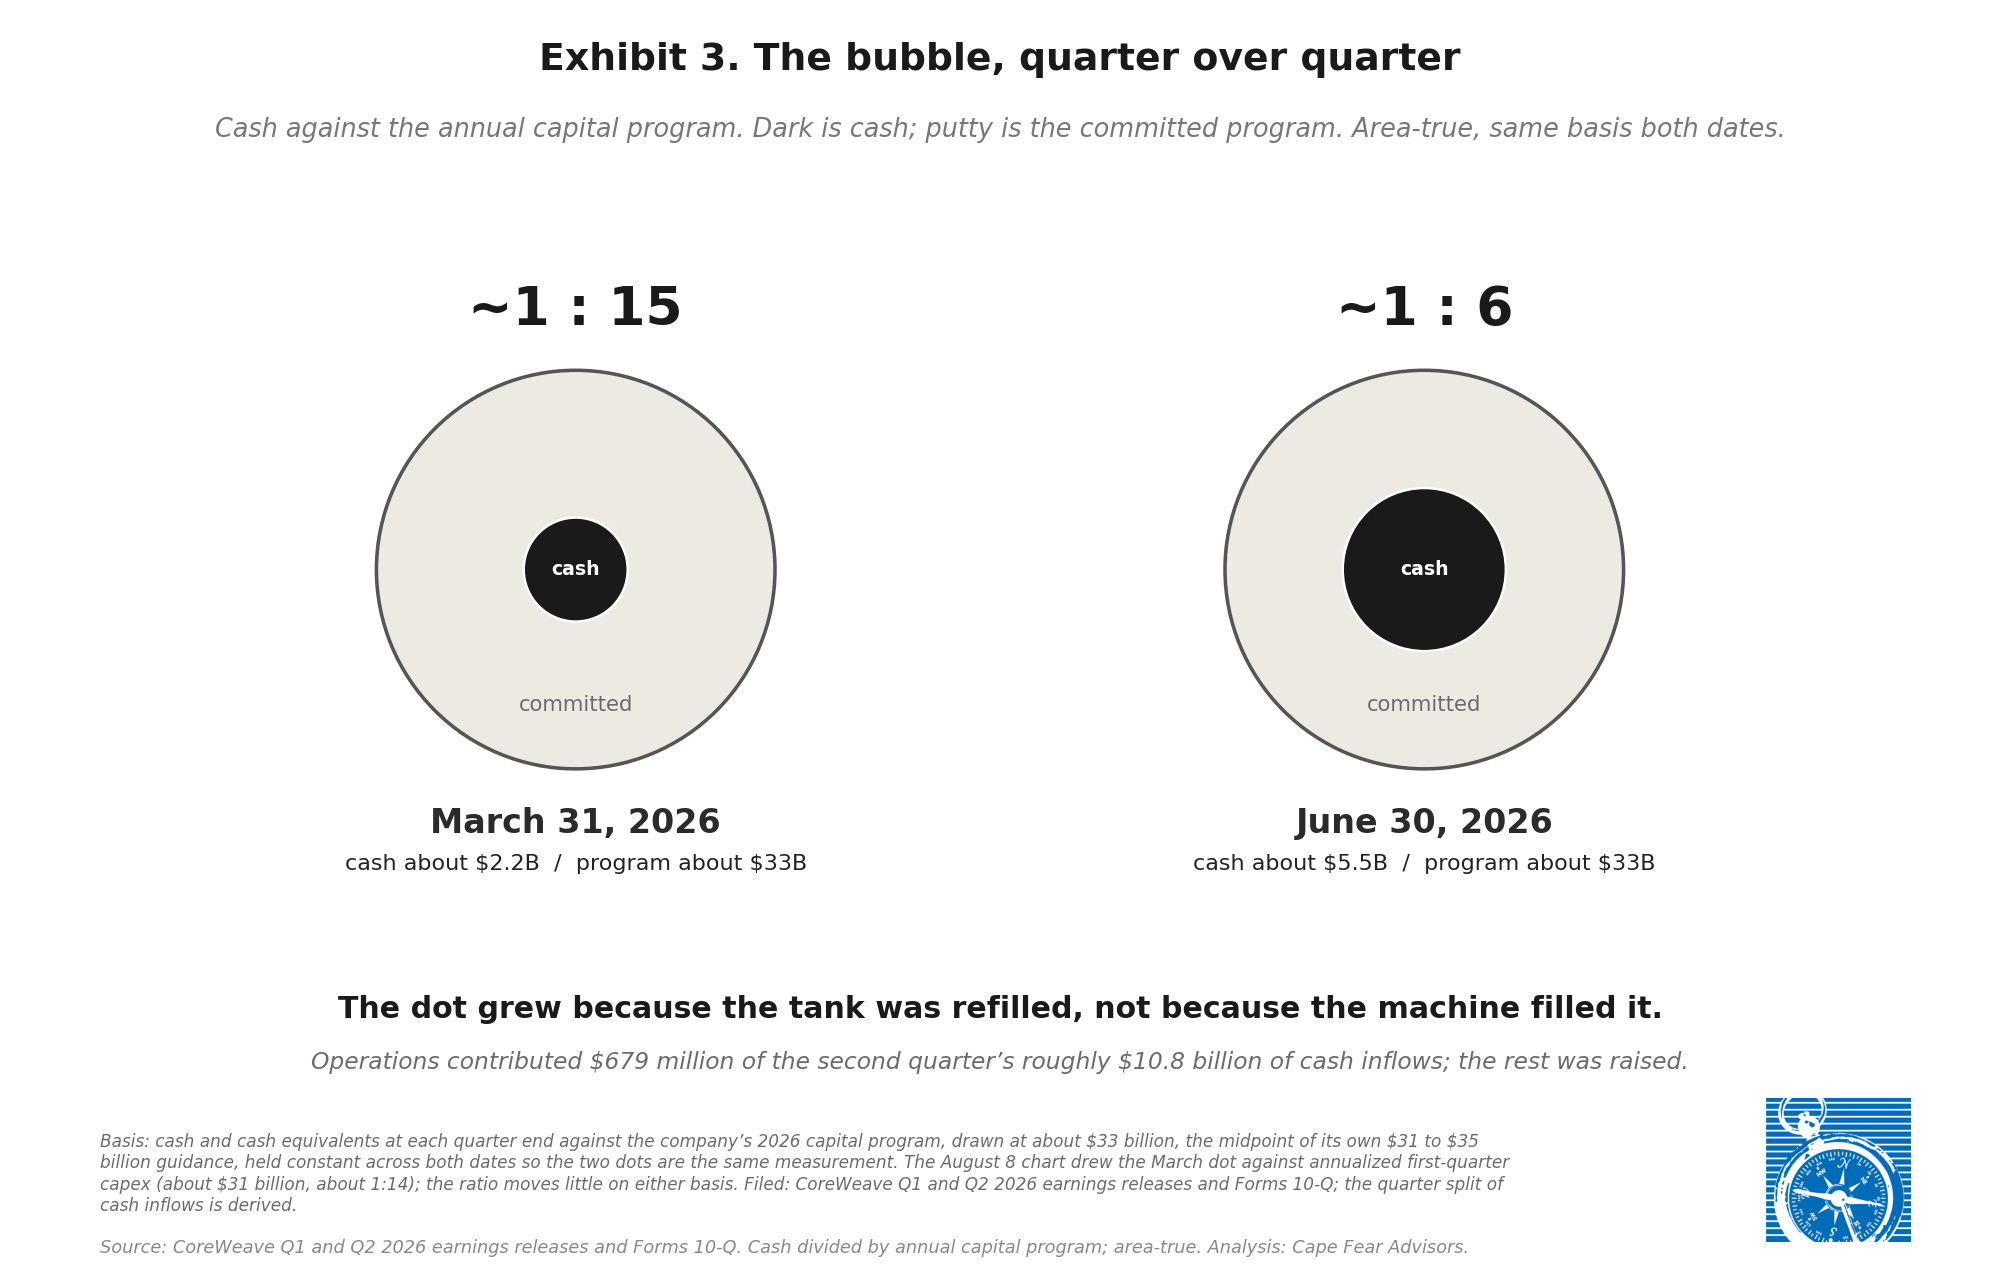
The quality-of-cash ratio moved with the tank. Cash on hand against the annual capital program ran near one to fifteen at March 31 and near one to six at June 30. The improvement is real. It is not earned; it is borrowed. Operations contributed $679 million of the quarter’s roughly $10.8 billion of cash inflows, and the rest was raised. The dot grew because the tank was refilled, not because the machine filled it.
A fifth reading, ours: how is the future presented?
The August piece did not ask this one; the print put it in front of us. The CFO called the first quarter’s one percent adjusted operating margin “the trough.” The second quarter printed five percent. One data point is not a trend; the claim survived its first test. Adjusted EBITDA margin printed at 59 percent. Active power reached 1.5 gigawatts against roughly 3.7 contracted, both ends of the ratio disclosed, the only base-attached utilization figure we have seen among the filers we read.
Beside those numbers sit these. Adjusted operating income of $128 million against net interest expense of $640 million, a five-fold gap between the profitability measure management leads with and the single largest cash cost beneath it. The measures that improved are measures the company defines. The measures that did not improve require no definition: operating cash flow of $679 million in the quarter, on our derivation, against $640 million of net interest.
The $1.4 billion, taken as a whole
In July we wrote that the three statements, each correct under its own rules, present three different businesses, and that the reader who wants the one company must hold all three at once. The round trip is that piece’s second verse. It is a revenue recognition issue because deferred revenue is the waiting room for revenue, and the auditor’s flagged judgment is “the identification and treatment of contract terms that may impact the timing and amount of revenue recognized.” A billion and a half dollars left that waiting room, lived one quarter under a caption the filing left undefined, and returned. Every future quarter’s revenue draws from a balance this movement passed through twice.
It is an internal controls conundrum because the same 10-Q states that material weaknesses, in IT general controls, segregation of duties, and personnel, continued to exist at June 30. The round trip was narrated in one direction and silent in the other, in periods no auditor has audited, under a control environment management itself flags. The first audited statements that must carry this arc, and the first auditor attestation on the controls that produced it, arrive together in the FY2026 annual report. That is now the most important date on our calendar for this name.
Nothing in this piece identifies an error, an inconsistency with the accounting rules, or a bad actor. Interim reclassifications are permitted. Captions come and go. The subject is the asymmetry: a departure with a sentence, and a return the reader must derive.
The sum of the participants
A note on what this piece does not contain: a valuation. A discounted cash flow model run on the consolidated firm does not produce one. On the filed trajectory, the crossing point where returns on invested capital clear the cost of the capital sits beyond any horizon a model can defend. That is not a fault of the company, and it is not a fault of the method. It is the method reporting that the answer is not yet in the numbers.
What the numbers do contain is participants. A supplier that is also a shareholder. Lenders across seven named facilities since 2023. Customers holding order forms, and one holding stock. Landlords carrying $16.3 billion of operating lease liabilities. A public float. Each row’s cash terms are filed, and each row presents different bases, different time frames, and different remedies. The bull case and the bear case need the same addition: what each participant puts in, what each takes out, and where each return accrues. The equity’s line in that addition is computed last, after every senior row clears, and it stays out of reach until the assumed debt inflows, and the round trips beneath them, have run their course. Against the model’s time frame, those differences are the analysis. Some rows will complete their round trips entirely before the equity’s line is measurable at all. In the newest credit agreement, cash steps through a nine-rung waterfall, and distributions are the ninth rung.
And one round trip is not the journey. The facilities carry five-year terms against a question that answers in decades; in July we counted the refinancing requirement near four and a half turns before the machines pay for themselves and for the money that bought them. This year the turns repriced: SOFR plus 4.50 in May, SOFR plus 5.50 in August, one hundred basis points in eleven weeks, like for like. Each repricing raises what the machines must earn before anything reaches the ninth rung, and each one moves the equity’s answer date further out, with the price of the wait set again at every turn. Every participant carries that repricing, and none carries it alike. The lenders carry it with collateral, covenants, and remedies, repriced quarterly. The landlords carry it with leases. Some participants carry it with returns that accrue on their own ledgers, outside this firm’s. The float carries it with a mark. The round trip this quarter documented is what one turn looks like from the outside. The ledger of who rides them is a piece of its own.
What has to happen next, still
In July we counted twenty-seven years against a schedule that gives the machines six. In August we asked four questions. One is retired: the $1.3 billion resolved as a reversal. The other three renew each quarter, and two dates now hold them. The FY2026 10-K, where the round trip meets its first audit and the controls meet their first attestation. And roughly February 2027, when the newest facility’s debt service coverage test begins to run. Two clocks, as before. The financing clock is running, and repriced one hundred basis points heavier. The return clock is running, and this quarter it did not move.
Standing disclosure
Nothing here is investment advice. Cape Fear Advisors holds no direct position, long or short, in CoreWeave, NVIDIA, or Meta Platforms; any exposure is indirect, through managed funds it does not control, which may now include index funds holding the public companies named. Anthropic is the developer of Claude, which is used in preparing this research, and CoreWeave has named Anthropic among its customers (Note 5); no claim in this piece rests on trust in the tool, since every figure names its filing, the derivations show their arithmetic, and the reading is reproducible from the public accessions. NVIDIA, discussed above as supplier and shareholder, is the maker of the GPUs the customer contracts specify and an investor in CoreWeave; Meta and OpenAI hold the order forms cited; Jane Street holds the investment and purchase commitment cited; each is discussed only in its filed role. Companies not named here, among them the lenders under the facilities and the customers behind the concentration percentages, may hold positions or supply relationships that bear on the filers discussed, and that possibility is part of why every piece is checked against ground facts and filings rather than a fixed list. Figures are quoted from the filers without characterization, and the same standard of reading is applied to every filer named.
NOTES
“CoreWeave: What Has to Happen Next,” Cape Fear Advisors, August 3, 2026. The four questions are from that piece as published; the second is quoted in full above, and where a section heading compresses the published wording, the published text controls. Also “CoreWeave, Twenty-Seven Years” (July 12, 2026) and “CoreWeave, Taken as a Whole” (July 2026).
“CoreWeave, Adding It Up: One Filing, Two Announcements,” Cape Fear Advisors, August 11, 2026, including the same-day dated correction regarding Jane Street’s April 15 investment.
CoreWeave Q2 2026 Form 10-Q (accession 0001769628-26-000366): balance sheet components note; revenue note; statements of cash flows and supplemental disclosures; risk factors; controls and procedures. Q1 2026 Form 10-Q (accession 0001769628-26-000222): Note 7 itemization of customer liabilities; the reclassification sentence in the revenue note. FY2025 Form 10-K (accession 0001769628-26-000104): absence of the caption; other current liabilities presentation.
All derivations (the quarter-alone cash flow decomposition, the non-cash round trip arithmetic, the coverage and quality-of-cash ratios) are ours from the filed figures and carry residuals under $100 million; the filed figures control wherever they differ. The seven named term facilities: DDTL 1.0 ($2.3 billion, July 2023); 2.0 ($7.6 billion, May 2024); 2.1 (an increase of $3.0 billion, September 2025); 3.0 ($2.6 billion, July 2025); 4.0 ($8.5 billion, March 2026); 5.0 ($3.1 billion, May 2026); 5.5 ($2.6 billion, August 2026), per the Q2 10-Q’s risk factors. The family numbering is not chronological; the dates are as filed, and the maturity schedule in the debt note (DDTL 3.0 due August 2030, DDTL 2.1 due March 2031) corroborates the order.
CoreWeave named Anthropic among its customers in its Q1 2026 earnings release (accession 0001769628-26-000220, May 7, 2026): “Signed multi-year agreement with Anthropic to support the development and deployment of Anthropic’s Claude family of AI models.”